Foreign Investment in the Oil Sands and British Columbia Shale Gas
Total Page:16
File Type:pdf, Size:1020Kb
Load more
Recommended publications
-

Cenovus Reports Second-Quarter 2020 Results Company Captures Value by Leveraging Flexibility of Its Operations Calgary, Alberta (July 23, 2020) – Cenovus Energy Inc
Cenovus reports second-quarter 2020 results Company captures value by leveraging flexibility of its operations Calgary, Alberta (July 23, 2020) – Cenovus Energy Inc. (TSX: CVE) (NYSE: CVE) remained focused on financial resilience in the second quarter of 2020 and used the flexibility of its assets and marketing strategy to adapt quickly to the changing external environment. This positioned the company to weather the sharp decline in benchmark crude oil prices in April by reducing volumes at its oil sands operations and storing the mobilized oil in its reservoirs for production in an improved price environment. While Cenovus’s financial results were impacted by the weak prices early in the quarter, the company captured value by quickly ramping up production when Western Canadian Select (WCS) prices increased almost tenfold from April to an average of C$46.03 per barrel (bbl) in June. As a result of this decision, Cenovus reached record volumes at its Christina Lake oil sands project in June and achieved free funds flow for the month of more than $290 million. “We view the second quarter as a period of transition, with April as the low point of the downturn and the first signs of recovery taking hold in May and June,” said Alex Pourbaix, Cenovus President & Chief Executive Officer. “That said, we expect the commodity price environment to remain volatile for some time. We believe the flexibility of our assets and our low cost structure position us to withstand a continued period of low prices if necessary. And we’re ready to play a significant -
2021 Annual General Meeting and Proxy Statement 2020 Annual Report
2020 Annual Report and Proxyand Statement 2021 Annual General Meeting Meeting General Annual 2021 Transocean Ltd. • 2021 ANNUAL GENERAL MEETING AND PROXY STATEMENT • 2020 ANNUAL REPORT CONTENTS LETTER TO SHAREHOLDERS NOTICE OF 2021 ANNUAL GENERAL MEETING AND PROXY STATEMENT COMPENSATION REPORT 2020 ANNUAL REPORT TO SHAREHOLDERS ABOUT TRANSOCEAN LTD. Transocean is a leading international provider of offshore contract drilling services for oil and gas wells. The company specializes in technically demanding sectors of the global offshore drilling business with a particular focus on ultra-deepwater and harsh environment drilling services, and operates one of the most versatile offshore drilling fleets in the world. Transocean owns or has partial ownership interests in, and operates a fleet of 37 mobile offshore drilling units consisting of 27 ultra-deepwater floaters and 10 harsh environment floaters. In addition, Transocean is constructing two ultra-deepwater drillships. Our shares are traded on the New York Stock Exchange under the symbol RIG. OUR GLOBAL MARKET PRESENCE Ultra-Deepwater 27 Harsh Environment 10 The symbols in the map above represent the company’s global market presence as of the February 12, 2021 Fleet Status Report. ABOUT THE COVER The front cover features two of our crewmembers onboard the Deepwater Conqueror in the Gulf of Mexico and was taken prior to the COVID-19 pandemic. During the pandemic, our priorities remain keeping our employees, customers, contractors and their families healthy and safe, and delivering incident-free operations to our customers worldwide. FORWARD-LOOKING STATEMENTS Any statements included in this Proxy Statement and 2020 Annual Report that are not historical facts, including, without limitation, statements regarding future market trends and results of operations are forward-looking statements within the meaning of applicable securities law. -

Cenovus Energy Inc. (CVE) – Quality and Growth for the Patient Investor
Portfolio Advisory Group Cenovus Energy Inc. (CVE) – Quality and Growth For The Patient Investor Cenovus was created through the split of Calgary-based Primer on the Oil Sands and energy company EnCana into two separate organizations in late 2009. As a result of this split, many Canadian Steam-Assisted-Gravity-Drainage investors found themselves holding two very different (SAGD) investments: a pure-play natural gas company (EnCana) Including the oil sands, Canada’s oil reserves are the and an integrated oil & gas company (Cenovus). This second largest in the world. Oil sands are composed document aims to provide some insight into the nature primarily of sand, clay, bitumen and water. Bitumen and long-term potential of Cenovus. is the product of oil sands production – a thick oil Cenovus owns oil sands projects that have a tremendous embedded in sand. growth profile over the next decade and are widely Recovery of bitumen is typically achieved by one of viewed as some of the highest-quality assets in the two methods: mining in open pits or drilling. Bitumen industry. However, since inception, the shares of extraction using drilling is referred to as in situ recovery, Cenovus have largely traded within a range. One reason and is generally used for reservoirs that are too deep for is that the company has made a trade-off between near- surface mining techniques to work economically. It is term and future production by drawing cash flows from estimated that approximately 80% of the total bitumen its natural gas business to fund growth in its oil sands recoverable in Alberta can only be produced with in business. -

Case M.9837 — BP/Sinopec Fuel Oil Sales/BP Sinopec Marine Fuels) Candidate Case for Simplified Procedure
C 6/16 EN Offi cial Jour nal of the European Union 8.1.2021 Prior notification of a concentration (Case M.9837 — BP/Sinopec Fuel Oil Sales/BP Sinopec Marine Fuels) Candidate case for simplified procedure (Text with EEA relevance) (2021/C 6/13) 1. On 22 December 2020, the Commission received notification of a proposed concentration pursuant to Article 4 of Council Regulation (EC) No 139/2004 (1). This notification concerns the following undertakings: — BP Plc. (United Kingdom), — Sinopec Fuel Oil Sales Co. Ltd (People’s Republic of China), controlled by China Petrochemical Corporation (People’s Republic of China), — BP Sinopec Marine Fuels Pte. Ltd. BP Plc. and Sinopec Fuel Oil Sales Co. Ltd acquire within the meaning of Article 3(1)(b) and 3(4) of the Merger Regulation joint control of BP Sinopec Marine Fuels Pte. Ltd. The concentration is accomplished by way of contract. 2. The business activities of the undertakings concerned are: — for BP Plc.: exploration, production and marketing of crude oil and natural gas; refining, marketing, supply and transportation of petroleum products; production and supply of petrochemicals and related products; and supply of alternative energy, — for Sinopec Fuel Oil Sales Co. Ltd: providing oil products and service to domestic and international trading vessels, — BP Sinopec Marine Fuels Pte. Ltd: wholesale and retail supply of bunker fuels in Europe, Asia and the Middle East. 3. On preliminary examination, the Commission finds that the notified transaction could fall within the scope of the Merger Regulation. However, the final decision on this point is reserved. Pursuant to the Commission Notice on a simplified procedure for treatment of certain concentrations under the Council Regulation (EC) No 139/2004 (2) it should be noted that this case is a candidate for treatment under the procedure set out in the Notice. -
Empirical Inference of Related Trading Between Two Securities: Detecting Pairs Trading, Merger Arbitrage, and Strategy Rules*
Empirical inference of related trading between two securities: Detecting pairs trading, merger arbitrage, and strategy rules* Keith Godfrey The University of Western Australia Working paper: 5 September 2013 The traditional approach to studying pairs trading is to simulate profitability using ex-post historical prices. I study the actual trades reported anonymously in security pairs and build statistical inferences of related trading. The approach is based on the time differences between trades. It can distinguish intrinsically related securities from pseudo-random sets, find stocks involved in merger arbitrage in massive sets of paired index constituents, and infer dominant trading rules of mean reversion algorithms. Empirical inference of related trading can enable further studies into pairs trading, strategy rules, merger arbitrage, and insider trading. Keywords: Inferred trading, empirical inference, pairs trading, merger arbitrage. JEL Classification Codes: G00, G10, C10, C40, C60 The availability of intraday trading or “tick” data with time resolution of a millisecond or finer is opening many avenues of research into financial markets. Analysis of two or more streams of tick data concurrently is becoming increasingly important in the study of multiple-security trading including index tracking, pairs trading, merger arbitrage, and market-neutral strategies. One of the greatest challenges in empirical trading research is the anonymity of reported trades. Securities exchanges report the dates, times, prices, and volumes traded, without identifying the traders. In studies of a single security, this introduces uncertainty of whether each market order that caused a trade was the buy or sell order, and there are documented approaches of inference such as Lee and Ready (1991). -
Initial Project Description Summary
SUNCOR ENERGY INC. Base Mine Extension INITIAL PROJECT DESCRIPTION SUMMARY February 2020 SUNCOR ENERGY INC. Base Mine Extension - Initial Project Description Summary February 2020 This Page Intentionally Left Blank SUNCOR ENERGY INC. Base Mine Extension - Initial Project Description Summary February 2020 EXECUTIVE SUMMARY Suncor Energy Inc. (Suncor) is submitting a proposal to develop the Base Mine Extension Project (the Project). All plausible pathways to address global emissions need energy from fossil fuels and Suncor views Canada’s world class, strategic oil sands resource as a key part of the energy future for decades to come. Commensurate with Canada’s ambitions, Suncor is committed to a long-term strategy of reducing absolute emissions. With the innovation we are known for, Suncor can provide the world with trusted low carbon energy. Suncor has invested billions of dollars in infrastructure that produces value added products to meet the energy needs of Albertans and Canadians. This Project is necessary to continue to add value with this infrastructure. The bitumen from this project will be used to supply the existing upgraders at Suncor’s Oil Sands Base Plant operations (Base Plant), when the existing mines are depleted. The Project is adjacent to Base Plant and includes an open pit mining operation and extraction facilities. Production is expected to be nominally 225 thousand barrels per day of replacement bitumen during its estimated 25-year operational life. The Project application will be based on best-available technology. In parallel, Suncor is developing new technologies, such as non-aqueous extraction. These new technologies have the potential to significantly reduce the overall footprint, reclamation timeline, and GHG emissions of mining and will be incorporated as appropriate. -
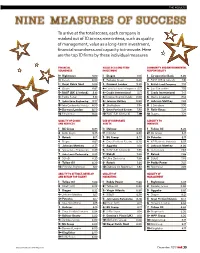
To Arrive at the Total Scores, Each Company Is Marked out of 10 Across
BRITAIN’S MOST ADMIRED COMPANIES THE RESULTS 17th last year as it continues to do well in the growing LNG business, especially in Australia and Brazil. Veteran chief executive Frank Chapman is due to step down in the new year, and in October a row about overstated reserves hit the share price. Some pundits To arrive at the total scores, each company is reckon BG could become a take over target as a result. The biggest climber in the top 10 this year is marked out of 10 across nine criteria, such as quality Petrofac, up to fifth from 68th last year. The oilfield of management, value as a long-term investment, services group may not be as well known as some, but it is doing great business all the same. Its boss, Syrian- financial soundness and capacity to innovate. Here born Ayman Asfari, is one of the growing band of are the top 10 firms by these individual measures wealthy foreign entrepreneurs who choose to make London their operating base and home, to the benefit of both the Exchequer and the employment figures. In fourth place is Rolls-Royce, one of BMAC’s most Financial value as a long-term community and environmental soundness investment responsibility consistent high performers. Hardly a year goes past that it does not feature in the upper reaches of our table, 1= Rightmove 9.00 1 Diageo 8.61 1 Co-operative Bank 8.00 and it has topped its sector – aero and defence engi- 1= Rotork 9.00 2 Berkeley Group 8.40 2 BASF (UK & Ireland) 7.61 neering – for a decade. -

Cenovus Completes Acquisition of Assets in Western Canada from Conocophillips
Cenovus completes acquisition of assets in Western Canada from ConocoPhillips Calgary, Alberta (May 17, 2017) – Cenovus Energy Inc. (TSX: CVE) (NYSE: CVE) has closed its previously announced purchase of assets in Western Canada from ConocoPhillips after receiving all necessary regulatory approvals for the transaction. The acquired assets include ConocoPhillips’ 50% interest in the FCCL Partnership, the oil sands venture which was jointly owned with and operated by Cenovus, as well as the majority of ConocoPhillips’ Deep Basin conventional assets in Alberta and British Columbia. “With the completion of this transformational deal, we now have full control of our best-in- class oil sands projects and an exciting new growth platform in the Deep Basin that provides us with significant short-cycle development opportunities to complement our long-term oil sands growth portfolio,” said Brian Ferguson, Cenovus President & Chief Executive Officer. “As a result of this transaction, we’ve now doubled our production and reserves base.” In the coming months, Cenovus will remain firmly focused on: • Continuing to safely and reliably operate all of its assets • Efficiently integrating the Deep Basin assets and staff into the company • Deleveraging its balance sheet, including using the proceeds of planned divestitures, such as the sale of the company’s Pelican Lake and Suffield assets, which are currently being marketed. Cenovus intends to provide an update on its investment plans for its consolidated oil sands business and newly acquired Deep Basin -

National Oil Companies: Business Models, Challenges, and Emerging Trends
Corporate Ownership & Control / Volume 11, Issue 1, 2013, Continued - 8 NATIONAL OIL COMPANIES: BUSINESS MODELS, CHALLENGES, AND EMERGING TRENDS Saud M. Al-Fattah* Abstract This paper provides an assessment and a review of the national oil companies' (NOCs) business models, challenges and opportunities, their strategies and emerging trends. The role of the national oil company (NOC) continues to evolve as the global energy landscape changes to reflect variations in demand, discovery of new ultra-deep water oil deposits, and national and geopolitical developments. NOCs, traditionally viewed as the custodians of their country's natural resources, have generally owned and managed the complete national oil and gas supply chain from upstream to downstream activities. In recent years, NOCs have emerged not only as joint venture partners globally with the major oil companies, but increasingly as competitors to the International Oil Companies (IOCs). Many NOCs are now more active in mergers and acquisitions (M&A), thereby increasing the number of NOCs seeking international upstream and downstream acquisition and asset targets. Keywords: National Oil Companies, Petroleum, Business and Operating Models * Saudi Aramco, and King Abdullah Petroleum Studies and Research Center (KAPSARC) E-mail: [email protected] Introduction historically have mainly operated in their home countries, although the evolving trend is that they are National oil companies (NOCs) are defined as those going international. Examples of NOCs include Saudi oil companies that have significant shares owned by Aramco (the largest integrated oil and gas company in their parent government, and whose missions are to the world), Kuwait Petroleum Corporation (KPC), work toward the interest of their country. -
Preparing for Carbon Pricing: Case Studies from Company Experience
TECHNICAL NOTE 9 | JANUARY 2015 Preparing for Carbon Pricing Case Studies from Company Experience: Royal Dutch Shell, Rio Tinto, and Pacific Gas and Electric Company Acknowledgments and Methodology This Technical Note was prepared for the PMR Secretariat by Janet Peace, Tim Juliani, Anthony Mansell, and Jason Ye (Center for Climate and Energy Solutions—C2ES), with input and supervision from Pierre Guigon and Sarah Moyer (PMR Secretariat). The note comprises case studies with three companies: Royal Dutch Shell, Rio Tinto, and Pacific Gas and Electric Company (PG&E). All three have operated in jurisdictions where carbon emissions are regulated. This note captures their experiences and lessons learned preparing for and operating under policies that price carbon emissions. The following information sources were used during the research for these case studies: 1. Interviews conducted between February and October 2014 with current and former employees who had first-hand knowledge of these companies’ activities related to preparing for and operating under carbon pricing regulation. 2. Publicly available resources, including corporate sustainability reports, annual reports, and Carbon Disclosure Project responses. 3. Internal company review of the draft case studies. 4. C2ES’s history of engagement with corporations on carbon pricing policies. Early insights from this research were presented at a business-government dialogue co-hosted by the PMR, the International Finance Corporation, and the Business-PMR of the International Emissions Trading Association (IETA) in Cologne, Germany, in May 2014. Feedback from that event has also been incorporated into the final version. We would like to acknowledge experts at Royal Dutch Shell, Rio Tinto, and Pacific Gas and Electric Company (PG&E)—among whom Laurel Green, David Hone, Sue Lacey and Neil Marshman—for their collaboration and for sharing insights during the preparation of the report. -

Suncor Q3 2020 Investor Relations Supplemental Information Package
SUNCOR ENERGY Investor Information SUPPLEMENTAL Published October 28, 2020 SUNCOR ENERGY Table of Contents 1. Energy Sources 2. Processing, Infrastructure & Logistics 3. Consumer Channels 4. Sustainability 5. Technology Development 6. Integrated Model Calculation 7. Glossary SUNCOR ENERGY 2 SUNCOR ENERGY EnergyAppendix Sources 3 202003- 038 Oil Sands Energy Sources *All values net to Suncor In Situ Mining Firebag Base Plant 215,000 bpd capacity 350,000 bpd capacity Suncor WI 100% Suncor WI 100% 2,603 mmbbls 2P reserves1 1,350 mmbbls 2P reserves1 Note: Millennium and North Steepank Mines do not supply full 350,000 bpd of capacity as significant in-situ volumes are sent through Base Plant MacKay River Syncrude 38,000 bpd capacity Syncrude operated Suncor WI 100% 205,600 bpd net coking capacity 501 mmbbls 2P reserves1 Suncor WI 58.74% 1,217 mmbbls 2P reserves1 Future opportunities Fort Hills ES-SAGD Firebag Expansion Suncor operated Lewis (SU WI 100%) 105,000 bpd net capacity Meadow Creek (SU WI 75%) Suncor WI 54.11% 1,365 mmbbls 2P reserves1 First oil achieved in January 2018 SUNCOR ENERGY 1 See Slide Notes and Advisories. 4 1 Regional synergy opportunities for existing assets Crude logistics Upgrader feedstock optionality from multiple oil sands assets Crude feedstock optionality for Edmonton refinery Supply chain Sparing, warehousing & supply chain management Consolidation of regional contracts (lodging, busing, flights, etc.) Operational optimizations Unplanned outage impact mitigations In Situ Turnaround planning optimization Process -

Suncor Energy – Investor Presentation 2019 Q1
INVESTOR INFORMATION Q1 2019 Published May 1, 2019 2 Canada’s leading integrated energy company $85B ~940 mbpd ~600 mbpd 28+ years ~460 mbpd ~1750 1 Oil production Heavy upgrading 2P Reserve life Refining nameplate Enterprise value Retail sites4 As at March 31, 2019 nameplate capacity2 nameplate capacity2 index3 capacity2 1, 2, 3, 4 See Slide Notes and Advisories 3 Suncor – A resilient business focused on shareholder returns Cash flow growth Cash generation Strong potential FFO1 increase largely independent of market conditions Significant upside FFO1 sensitivity to WTI, based on TTM5 actuals US$62.80 WTI, 0.76 C$/US$, US$18.00 NYH 3-2-1 crack spread 2 (C$ billion) ~5% CAGR (Based on 2019 price guidance) $16 $14 TTM average production 750 mbbls/d $12 Debottlenecks, $10 cost reductions $8 Fort Hills, and margin Syncrude, improvements $6 and Hebron $4 $5.5B Sustaining capital6 + dividend $2 $2.8B Sustaining capital6 $0 2018 FFO1 Production Free funds flow 2023E FFO1 $60 $63 $70 $75 $80 growth 3 growth4 TTM WTI ($USD) Shareholder returns Resilience Commitment to reliable returns through the commodity cycles Managing the balance sheet as a strategic asset Dividend per share7 Liquidity Buyback per share7,8,9 Anticipated buyback per share7,9 7% $5.3B $1.9B cash and $3.4B in available lines of credit Dividend + buyback yield As at March 31, 2019 — 5% 5% A low Credit rating 1.88 Investment grade 0.85 DBRS (A Low) Stable, S&P(A-) stable, Moody’s (Baa1) Stable 1.14 3% 3% Baa1 WTI FFO Break-Even10 (USD) 1.02 1.14 1.16 1.28 1.44 1.68 ~$45 Sustaining capital6 + dividend 2014 2015 2016 2017 2018 2019E 2019 1, 2, 3, 4, 5, 6, 7, 8, 9, 10 See Slide Notes and Advisories.