RE-IMAGINING BIG OILS How Energy Companies Can Successfully Adapt to Climate Change
Total Page:16
File Type:pdf, Size:1020Kb
Load more
Recommended publications
-
2021 Annual General Meeting and Proxy Statement 2020 Annual Report
2020 Annual Report and Proxyand Statement 2021 Annual General Meeting Meeting General Annual 2021 Transocean Ltd. • 2021 ANNUAL GENERAL MEETING AND PROXY STATEMENT • 2020 ANNUAL REPORT CONTENTS LETTER TO SHAREHOLDERS NOTICE OF 2021 ANNUAL GENERAL MEETING AND PROXY STATEMENT COMPENSATION REPORT 2020 ANNUAL REPORT TO SHAREHOLDERS ABOUT TRANSOCEAN LTD. Transocean is a leading international provider of offshore contract drilling services for oil and gas wells. The company specializes in technically demanding sectors of the global offshore drilling business with a particular focus on ultra-deepwater and harsh environment drilling services, and operates one of the most versatile offshore drilling fleets in the world. Transocean owns or has partial ownership interests in, and operates a fleet of 37 mobile offshore drilling units consisting of 27 ultra-deepwater floaters and 10 harsh environment floaters. In addition, Transocean is constructing two ultra-deepwater drillships. Our shares are traded on the New York Stock Exchange under the symbol RIG. OUR GLOBAL MARKET PRESENCE Ultra-Deepwater 27 Harsh Environment 10 The symbols in the map above represent the company’s global market presence as of the February 12, 2021 Fleet Status Report. ABOUT THE COVER The front cover features two of our crewmembers onboard the Deepwater Conqueror in the Gulf of Mexico and was taken prior to the COVID-19 pandemic. During the pandemic, our priorities remain keeping our employees, customers, contractors and their families healthy and safe, and delivering incident-free operations to our customers worldwide. FORWARD-LOOKING STATEMENTS Any statements included in this Proxy Statement and 2020 Annual Report that are not historical facts, including, without limitation, statements regarding future market trends and results of operations are forward-looking statements within the meaning of applicable securities law. -

Professional Profile Expertise Recent Experience Education
Javaid Akhtar Partner PROFESSIONAL PROFILE [email protected] Dual qualified as a Solicitor of England and Wales and Advocate in Pakistan, +92 (51) 285 5890-2 Javaid specialises in acquisitions, oil and gas and arbitration and corporate and commercial matters. Javaid is the managing partner of the Islamabad 64, Nazimuddin Road, F- 8/4, Islamabad, Pakistan office of Vellani & Vellani and was earlier a partner of Amhurst Brown, which merged with Vellani & Vellani in 2018. https://www.linkedin.com/i n/javaid-akhtar-49051313/ RECENT EXPERIENCE EDUCATION ACQUISITIONS Represented local and multinational companies in the sale and Bachelor of Law (LL. B) King’s College London - 1991 purchase of assets and shares, particularly in the upstream oil and gas sector. Acted in the purchase of Austrian owned OMV companies in Pakistan EXPERTISE (2017-8) and UK owned Premier Oil companies in Pakistan (2016), and a substantial holding in a Pakistani oil marketing company to a Dispute Resolution middle-eastern company (2018). Earlier, acted in the sale of BP’s Mergers & Acquisitions, assets in Pakistan (2011-14), purchase of Tullow Pakistan (2014) and Restructuring and aspects of the sale of Petronas Carigali Pakistan (2011). Securities Acted on the buy-side in relation to the Government of Pakistan’s sale Oil & Gas of companies and assets (i.e. privatization), including sale of state interests in petroleum concessions; in Pakistan Steel Corporation and Pakistan State Oil Ltd. Apart from the customary suite of agreements, such transactions involved extensive due diligence and, often protracted, issues to be resolved with regulatory authorities (including the Directorate General (Petroleum Concessions), the Competition Commission of Pakistan and the Securities and Exchange Commission of Pakistan). -
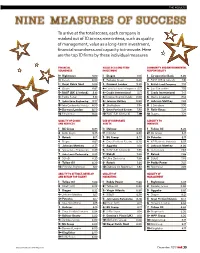
To Arrive at the Total Scores, Each Company Is Marked out of 10 Across
BRITAIN’S MOST ADMIRED COMPANIES THE RESULTS 17th last year as it continues to do well in the growing LNG business, especially in Australia and Brazil. Veteran chief executive Frank Chapman is due to step down in the new year, and in October a row about overstated reserves hit the share price. Some pundits To arrive at the total scores, each company is reckon BG could become a take over target as a result. The biggest climber in the top 10 this year is marked out of 10 across nine criteria, such as quality Petrofac, up to fifth from 68th last year. The oilfield of management, value as a long-term investment, services group may not be as well known as some, but it is doing great business all the same. Its boss, Syrian- financial soundness and capacity to innovate. Here born Ayman Asfari, is one of the growing band of are the top 10 firms by these individual measures wealthy foreign entrepreneurs who choose to make London their operating base and home, to the benefit of both the Exchequer and the employment figures. In fourth place is Rolls-Royce, one of BMAC’s most Financial value as a long-term community and environmental soundness investment responsibility consistent high performers. Hardly a year goes past that it does not feature in the upper reaches of our table, 1= Rightmove 9.00 1 Diageo 8.61 1 Co-operative Bank 8.00 and it has topped its sector – aero and defence engi- 1= Rotork 9.00 2 Berkeley Group 8.40 2 BASF (UK & Ireland) 7.61 neering – for a decade. -

Q4 News Release
Q4 News Release Calgary, February 2, 2021 TSE: IMO, NYSE American: IMO Imperial announces fourth quarter 2020 financial and operating results Fourth quarter net loss of $1,146 million, which includes a non-cash impairment charge of $1,171 million Cash generated from operations in the fourth quarter of $316 million, which includes unfavourable working capital effects of $218 million Highest quarterly upstream production in 30 years, driven by record production at Kearl Exceeded full-year cost reduction targets, with production and manufacturing expenses down $985 million from 2019, representing a savings of 15 percent compared to 2019 Full-year capital expenditures of $874 million, in line with the company’s most recent guidance, and less than half of 2019 expenditures Maintained dividend throughout the year, returning over $900 million to shareholders through dividends and share purchases in 2020 Fourth quarter Twelve months millions of Canadian dollars, unless noted 2020 2019 ∆I 2020 2019 ∆I Net income (loss) (U.S. GAAP) (1,146) 271 -1,417 (1,857) 2,200 -4,057 Net income (loss) per common share, assuming dilution (dollars) (1.56) 0.36 -1.92 (2.53) 2.88 -5.41 Capital and exploration expenditures 195 414 -219 874 1,814 -940 “The past year has proved an exceptionally challenging one, not only for the company and our employees, but society at-large,” said Brad Corson, chairman, president and chief executive officer. “Against significant headwinds, Imperial’s operational performance and cost management efforts have exceeded expectations. We set aggressive targets for capital and expense reductions in the first quarter of 2020, and we surpassed those targets. -

Imperial Standard: Imperial Oil, Exxon, and the Canadian Oil Industry from 1880
University of Calgary PRISM: University of Calgary's Digital Repository University of Calgary Press University of Calgary Press Open Access Books 2019-04 Imperial Standard: Imperial Oil, Exxon, and the Canadian Oil Industry from 1880 Taylor, Graham D. University of Calgary Press Taylor, G. D. (2019). Imperial Standard: Imperial Oil, Exxon, and the Canadian Oil Industry from 1880. "University of Calgary Press". http://hdl.handle.net/1880/110195 book https://creativecommons.org/licenses/by-nc-nd/4.0 Downloaded from PRISM: https://prism.ucalgary.ca IMPERIAL STANDARD: Imperial Oil, Exxon, and the Canadian Oil Industry from 1880 Graham D. Taylor ISBN 978-1-77385-036-8 THIS BOOK IS AN OPEN ACCESS E-BOOK. It is an electronic version of a book that can be purchased in physical form through any bookseller or on-line retailer, or from our distributors. Please support this open access publication by requesting that your university purchase a print copy of this book, or by purchasing a copy yourself. If you have any questions, please contact us at [email protected] Cover Art: The artwork on the cover of this book is not open access and falls under traditional copyright provisions; it cannot be reproduced in any way without written permission of the artists and their agents. The cover can be displayed as a complete cover image for the purposes of publicizing this work, but the artwork cannot be extracted from the context of the cover of this specific work without breaching the artist’s copyright. COPYRIGHT NOTICE: This open-access work is published under a Creative Commons licence. -

Slovenia: MOL Group' Retail Acquirement Agreement With
Slovenia: MOL Group’ retail acquirement agreement with OMV The agreed purchase price is 301 million euros (100 % share of OMV Slovenia); MOL Group reached an agreement with OMV to acquire OMV’s 92.25 % stake in OMV Slovenia, in which Croatian INA already holds a 7.75 % minority stake, from OMV Downstream GmbH as direct shareholder. The transaction includes 120 petrol stations across Slovenia. OMV Slovenia operates in the country under 3 brands: OMV (108), EuroTruck (4) and Avanti/DISKONT (8). MOL Group and INA will become the 100 % owner of the wholesale business of the acquired company, as well. With 48 MOL and 5 INA-branded service stations in Slovenia, MOL Group is currently the third largest retail market-player. However, the transaction is still subject to merger clearance. The acquisition fits into the Group’s SHAPE TOMORROW 2030+ updated long-term strategy, which places a special emphasis on the development of Consumer Services. MOL Group CEO Zsolt Hernadi said that this step is in line with group’s strategic goals to further expand retail fuel network in existing and potential new markets in central and eastern Europe. By 2025, MOL Group would like to reach 2200 petrol stations, potentially more, if more good opportunities arise. With constant development and digitization, shaping future consumer and mobility trends, MOL offers convenience as it aims to help people on the move, regardless of what powers the customer’s mode of transport. Furthermore, its integrated business model and accelerating growth enables it to provide financial resources for developing sustainable solutions and boosting circular economy in the region. -
Global Voting Activity Report to March 2021
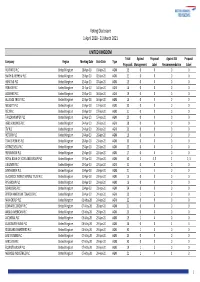
Voting Disclosure 1 April 2020 ‐ 31 March 2021 UNITED KINGDOM Total Against Proposal Against ISS Proposal Company Region Meeting Date Vote Date Type Proposals Management Label Recommmendation Label RIO TINTO PLC United Kingdom 08‐Apr‐20 01‐Apr‐20 AGM 25 0 0 00 SMITH & NEPHEW PLC United Kingdom 09‐Apr‐20 02‐Apr‐20 AGM 21 0 0 00 HUNTING PLC United Kingdom 15‐Apr‐20 07‐Apr‐20 AGM 15 0 0 00 PORVAIR PLC United Kingdom 21‐Apr‐20 14‐Apr‐20 AGM 14 0 0 00 AGGREKO PLC United Kingdom 23‐Apr‐20 16‐Apr‐20 AGM 19 0 0 00 ALLIANCE TRUST PLC United Kingdom 23‐Apr‐20 16‐Apr‐20 AGM 16 0 0 00 MEGGITT PLC United Kingdom 23‐Apr‐20 17‐Apr‐20 AGM 20 0 0 00 RELX PLC United Kingdom 23‐Apr‐20 17‐Apr‐20 AGM 21 0 0 00 TAYLOR WIMPEY PLC United Kingdom 23‐Apr‐20 17‐Apr‐20 AGM 20 0 0 00 HSBC HOLDINGS PLC United Kingdom 24‐Apr‐20 20‐Apr‐20 AGM 28 0 0 00 ITV PLC United Kingdom 24‐Apr‐20 20‐Apr‐20 AGM 21 0 0 00 ROTORK PLC United Kingdom 24‐Apr‐20 20‐Apr‐20 AGM 19 0 0 00 TRAVIS PERKINS PLC United Kingdom 28‐Apr‐20 21‐Apr‐20 AGM 20 0 0 00 ASTRAZENECA PLC United Kingdom 29‐Apr‐20 22‐Apr‐20 AGM 25 0 0 00 PERSIMMON PLC United Kingdom 29‐Apr‐20 22‐Apr‐20 AGM 17 0 0 00 ROYAL BANK OF SCOTLAND GROUP PLC United Kingdom 29‐Apr‐20 22‐Apr‐20 AGM 30 2 4, 5 22, 3 UNILEVER PLC United Kingdom 29‐Apr‐20 22‐Apr‐20 AGM 22 0 0 00 SYNTHOMER PLC United Kingdom 29‐Apr‐20 23‐Apr‐20 AGM 21 1 5 00 BLACKROCK WORLD MINING TRUST PLC United Kingdom 30‐Apr‐20 23‐Apr‐20 AGM 15 0 0 00 RPS GROUP PLC United Kingdom 30‐Apr‐20 23‐Apr‐20 AGM 16 0 0 00 SCHRODERS PLC United Kingdom 30‐Apr‐20 23‐Apr‐20 AGM 24 -
Smart Consumers in the Internet of Energy: Flexibility Markets & Services from Distributed Energy Resources 1/82
Monica Giulietti Chloé Le Coq Bert Willems Karim Anaya CERRE 2019 | Smart Consumers in the Internet of Energy: Flexibility Markets & Services from Distributed Energy Resources 1/82 The project, within the framework of which this report has been prepared, has received the support and/or input of the following organisations: Enel and Microsoft. As provided for in CERRE's by-laws and in the procedural rules from its “Transparency & Independence Policy”, this report has been prepared in strict academic independence. At all times during the development process, the research’s authors, the Joint Academic Directors and the Director General remain the sole decision-makers concerning all content in the report. The views expressed in this CERRE report are attributable only to the authors in a personal capacity and not to any institution with which they are associated. In addition, they do not necessarily correspond either to those of CERRE, or to any sponsor or to members of CERRE. © Copyright 2019, Centre on Regulation in Europe (CERRE) [email protected] www.cerre.eu CERRE 2019 | Smart Consumers in the Internet of Energy: Flexibility Markets & Services from Distributed Energy Resources 2/84 Table of contents Table of contents .............................................................................................................. 3 Table of Figures ................................................................................................................ 4 Acknowledgements ......................................................................................................... -

Analiza Efikasnosti Naftnih Kompanija U Srbiji Efficency Analysis of Oil Companies in Serbia
________________________________________________________________________ 79 Analiza efikasnosti naftnih kompanija u Srbiji Efficency Analysis of Oil Companies in Serbia prof. dr. sc. Radojko Lukić Ekonomski fakultet u Beogradu [email protected] Ključne reči: ekspolatacija sirove nafte i gasa, Abstract tržišno učešće, efikasnost poslovanja, financijske Lately, significant attention has been paid to the performanse, održivo izveštavanje evolution of the performance of oil companies around Key words: exploration of crude oil and gas, market the world, by individual regions and countries. Bearing share, business efficiency, financial performance, susta- this in mind, relying on the existing theoretical and inable reporting methodological and empirical results, this paper analyzes the efficiency of operations, financial perfor- mance and sustainable reporting of oil companies in Sažetak Serbia, with special emphasis on the Petroleum Industry of Serbia (NIS). The results of the survey show signifi- U poslednje vreme značajna se pažnja poklanja cant role of mining, i.e. oil companies in creating addi- evoluaciji performansi naftnih kompanija u svetu, tional value of the entire economy of Serbia. Concer- po pojedinim regionima i zemljama. Imajući to u ning the Petroleum Industry of Serbia, it has a signi- vidu, oslanjajući se na postojeće teorijsko-metodo- ficant place in the production and trade of petroleum loške i empirijske rezultate, u ovom radu se analizi- products in Serbia. For these reasons, the efficiency of raju efikasnosti poslovanja, finansijske performanse operations, financial performance and maintenance of i održivo izveštavanje naftnih kompanija u Srbiji, s the Petroleum Industry of Serbia has been complexly posebnim osvrtom na Naftnu industriju Srbije (NIS). analyzed. In this respect, according to many indicators, Rezultati istraživanja pokazuju značajnu ulogu rudar- it is at a satisfactory level in relation to the average of the stva, odnosno naftnih kompanija u kreiranju dodatne world’s leading oil companies. -

Big Oil's Real Agenda on Climate Change
Big Oil’s Real Agenda on Climate Change How the oil majors have spent $1bn since Paris on narrative capture and lobbying on climate March 2019 Big Oil’s Real Agenda on Climate Change How the oil majors have spent $1Bn since Paris on narrative capture and lobbying on climate Executive Summary .................................................................................................................................. 2 Introduction ................................................................................................................................................ 4 Detailed Results ........................................................................................................................................ 9 Big Oil and the US Elections ................................................................................................................ 17 Conclusions ............................................................................................................................................. 20 Appendix: Methodology ......................................................................................................................... 21 Appendix: Climate Scoring Profiles .................................................................................................. 22 1 InfluenceMap March 2019 Executive Summary ◼ This research finds that the five largest publicly-traded oil and gas majors (ExxonMobil, Royal Dutch Shell, Chevron, BP and Total) have invested over $1Bn of shareholder funds in the three -

Nordea 1 - European Value Fund BP - EUR This Fund Is Managed by Nordea Investment Funds S.A
25 May, 2020 Nordea 1 - European Value Fund BP - EUR This fund is managed by Nordea Investment Funds S.A. EFC Classification Equity Advanced Europe Price +/- Date 52wk range 44.57 EUR -0.41 22/05/2020 37.59 63.53 Issuer Profile Administrator Nordea Investment Funds S.A. The fund seeks to provide durable positive absolute returns by applying a disciplined Address 562, Rue de Neudorf 2220 value style approach. The managers consider themselves as business rather than stock market investors. Their approach concentrates on long-term investment and not on City Luxembourg market specific factors and short-term phenomena. This means focussing on selecting Tel/Fax + 352 43 39 50-1 businesses that will offer upside potential with limited downside risk. The belief that Website www.nordea.lu certain businesses have a greater earning power forms the basis of this process. Earning power is defined as a company‘s ability to generate substantial discretionary free cash flow over a sustained period of time. The managers believe that only in this way can a General Information company generate wealth for its shareholders, and provide long-term capital ISIN LU0064319337 appreciation. Investments are made on a business by business basis, irrespective of Fund Type Capitalization market capitalisation, sector or industry, and only when share prices represent a Quote Frequency daily significant discount to the intrinsic value of the business. Quote Currency EUR Currency EUR Chart 5 year Foundation Date 15/09/1989 Fund Manager Tom Stubbe Olsen Legal Type Investment -
UK/Netherlands SNS Hackathon Output Report
UK/Netherlands SNS Hackathon Output Report April 2019 Contents Foreword ............................................................................................................................................................. 3 Executive Summary ............................................................................................................................................. 4 Introduction ......................................................................................................................................................... 4 How Does a Hackathon Event Work? ................................................................................................................... 5 Findings ............................................................................................................................................................... 6 Operator Challenges ............................................................................................................................................ 7 Operator 1: Shell .......................................................................................................................................... 7 Operator2: Oranje Nassau Energie B.V. ........................................................................................................ 8 Operator 3: Spirit Energy .............................................................................................................................. 9 Operator 4: Neptune Energy ......................................................................................................................