Credit Institutions Register Section 1 Hereunder Lists All Credit Institutions Authorised Under Irish Legislation to Carry on Banking Business in the State
Total Page:16
File Type:pdf, Size:1020Kb
Load more
Recommended publications
-
NLFI Exit Advice ASR Nederland
Exit advice ASR Nederland NL financial investments 5 November 2015 10 15 20 25 30 35 40 45 50 55 Contents FOREWORD ...................................................................................................................................................... 3 SUMMARY & CONCLUSIONS ............................................................................................................................ 4 HISTORY PARLIAMENTARY DISCUSSION OF ASR SALE ...................................................................................... 8 5 PRECONDITIONS FOR SALE ......................................................................................................................................... 8 PARLIAMENTARY DEBATE SALES ADVICE AUGUST 2013 ................................................................................................... 8 PARLIAMENTARY DEBATE SALES ADVICE MAY 2014 ........................................................................................................ 9 SALES READINESS AND PRICE EXPECTATION .................................................................................................. 10 RESULTS ACHIEVED AND STRATEGY OF ASR ................................................................................................................. 10 10 READINESS FOR A TRANSACTION ............................................................................................................................... 11 Financial ...................................................................................................................................................... -

Kleinwort Hambros Strengthens UK Regional Presence with Senior Appointments
Kleinwort Hambros strengthens UK regional presence with senior appointments • Leigh Philpot announced as new Head of UK Regions • Chris Thomson new Deputy Head of UK Regions • Richard Brown and Mark Sinclair named Head of Yorkshire and Head of Cambridge Press release London, 14 February 2019 Kleinwort Hambros, one of the leading private bank and wealth manager’s in the UK, has today announced a series of senior appointments to bolster its regional presence across the UK. Leigh Philpot has been appointed the new Head of UK Regions, with immediate effect. In this newly created role, Leigh will be based in London and will report to Andrew Hillery, Head of UK Private Banking. He will be responsible for overseeing and implementing the UK regional strategy outside of London and strengthening its nationwide presence. Kleinwort Hambros currently has four regional offices in Newbury, Cambridge, Leeds and Edinburgh. Leigh previously headed up the Private Banking and Discretionary Fund Management team at Kleinwort Hambros. Most recently, Leigh created the bank’s IFA proposition, working alongside external advisers across the country to offer investment and private banking solutions to their clients. Prior to this, Leigh worked for Ely Fund Managers (now part of Rathbones) and Killik & Co, the advisory stockbrokers. To support Leigh, Chris Thomson has been named Deputy Head of UK Regions. This is in addition to his role as Head of the Edinburgh office, which he founded in 2008. Prior to Kleinwort Hambros, Chris spent twelve years in investment banking, split between London and New York. Richard Brown and Mark Sinclair have also recently been appointed Head of Yorkshire and Head of Cambridge, respectively. -

KBC Bank Ireland Summary Annual Report 2019
KBC Bank Ireland Summary Annual Report 2019 The bank of you KBC Bank Ireland plc is regulated by the Central Bank of Ireland. CONTENTS The Year in Review 02 Chairperson’s Statement 06 Chief Executive’s Review 08 Board of Directors 11 Executive Committee Members 16 Summary Consolidated Statement of Profit or Loss 17 Summary Consolidated Statement of Financial Position 18 Auditors’ Report 19 Corporate Governance 20 Sustainability 21 Contact KBC 26 About KBC 27 Management Team 28 1 2019 YEAR IN REVIEW KBC leads the way as the alternative banking choice in Ireland In 2019, we continued our journey to further develop and build a bank that offers innovative and competitive banking services and solutions in Ireland. We are delighted to have welcomed 40,000 new customers to KBC Bank Ireland in 2019. 2 Offering more choice and building long term value for our customers During the year we introduced free day-to-day banking for KBC Extra Current Account holders who make a monthly lodgement of €2,000, with no requirement to maintain a minimum balance making it one of the most competitive current accounts on the market. Irish people are responding to KBC’s competitive current account offering, including students, with 38,000 new current accounts opened in 2019, the strongest year since the launch of the current account in 2013. We reduced our 2 and 10-year fixed mortgage rates between 0.20% and 0.55% while maintaining our market leading position on 1 and 10-year fixed rates and offering some of the most competitive 2, 3 and 5-year fixed rates options. -
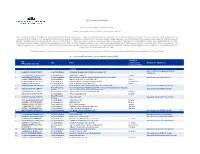
List of Supervised Entities (As of 1 September 2020)
List of supervised entities Cut-off date for changes: 1 September 2020 Number of significant entities directly supervised by the ECB: 114 This list displays the significant supervised entities, which are directly supervised by the ECB (part A) and the less significant supervised entities which are indirectly supervised by the ECB (Part B). Based on Article 2(20) of Regulation (EU) No 468/2014 of the European Central Bank of 16 April 2014 establishing the framework for cooperation within the Single Supervisory Mechanism between the European Central Bank and national competent authorities and with national designated authorities (OJ L 141, 14.5.2014, p. 1 - SSM Framework Regulation) a ‘supervised entity’ means any of the following: (a) a credit institution established in a participating Member State; (b) a financial holding company established in a participating Member State; (c) a mixed financial holding company established in a participating Member State, provided that the coordinator of the financial conglomerate is an authority competent for the supervision of credit institutions and is also the coordinator in its function as supervisor of credit institutions (d) a branch established in a participating Member State by a credit institution which is established in a non-participating Member State. The list is compiled on the basis of significance decisions which have been adopted and notified by the ECB to the supervised entity and that have become effective up to the cut-off date. A. List of significant entities directly supervised by the ECB Country of LEI Type Name establishment Grounds for significance MFI code for branches of group entities Belgium Article 6(5)(b) of Regulation (EU) No 1 LSGM84136ACA92XCN876 Credit Institution AXA Bank Belgium SA ; AXA Bank Belgium NV 1024/2013 CVRWQDHDBEPUUVU2FD09 Credit Institution AXA Bank Europe SCF France 2 549300NBLHT5Z7ZV1241 Credit Institution Banque Degroof Petercam SA ; Bank Degroof Petercam NV Significant cross-border assets 54930017BFF0C5RWQ245 Credit Institution Banque Degroof Petercam France S.A. -

Chronology, 1963–89
Chronology, 1963–89 This chronology covers key political and economic developments in the quarter century that saw the transformation of the Euromarkets into the world’s foremost financial markets. It also identifies milestones in the evolu- tion of Orion; transactions mentioned are those which were the first or the largest of their type or otherwise noteworthy. The tables and graphs present key financial and economic data of the era. Details of Orion’s financial his- tory are to be found in Appendix IV. Abbreviations: Chase (Chase Manhattan Bank), Royal (Royal Bank of Canada), NatPro (National Provincial Bank), Westminster (Westminster Bank), NatWest (National Westminster Bank), WestLB (Westdeutsche Landesbank Girozentrale), Mitsubishi (Mitsubishi Bank) and Orion (for Orion Bank, Orion Termbank, Orion Royal Bank and subsidiaries). Under Orion financings: ‘loans’ are syndicated loans, NIFs, RUFs etc.; ‘bonds’ are public issues, private placements, FRNs, FRCDs and other secu- rities, lead managed, co-managed, managed or advised by Orion. New loan transactions and new bond transactions are intended to show the range of Orion’s client base and refer to clients not previously mentioned. The word ‘subsequently’ in brackets indicates subsequent transactions of the same type and for the same client. Transaction amounts expressed in US dollars some- times include non-dollar transactions, converted at the prevailing rates of exchange. 1963 Global events Feb Canadian Conservative government falls. Apr Lester Pearson Premier. Mar China and Pakistan settle border dispute. May Jomo Kenyatta Premier of Kenya. Organization of African Unity formed, after widespread decolonization. Jun Election of Pope Paul VI. Aug Test Ban Take Your Partners Treaty. -

The London School of Economics and Political Science
The London School of Economics and Political Science Thesis Foreign Government Loan Issues on the London Capital Market, 1870 - 1913, with Special Reference to Japan by Toshio SUZUKI A Thesis submitted to the University of London for the Degree of Doctor of Philosophy, 1991 February UMI Number: U050B50 All rights reserved INFORMATION TO ALL USERS The quality of this reproduction is dependent upon the quality of the copy submitted. In the unlikely event that the author did not send a complete manuscript and there are missing pages, these will be noted. Also, if material had to be removed, a note will indicate the deletion. Dissertation Publishing UMI U050B50 Published by ProQuest LLC 2014. Copyright in the Dissertation held by the Author. Microform Edition © ProQuest LLC. All rights reserved. This work is protected against unauthorized copying under Title 17, United States Code. ProQuest LLC 789 East Eisenhower Parkway P.O. Box 1346 Ann Arbor, Ml 48106-1346 F 6&'F- x6( I o 7<>c Abstract This thesis examines foreign government loan issues on the London capital market in the period from 1870 to 1913, with special reference to Japan. Chapter One provides an overview of foreign government loan issues in London. Chapter Two deals with a number of more specific topics: the development of the loan issue organisations on the market, and the role and involvement of various types of financial institutions in loan issue business. Later Chapters mainly take up the detailed history of Japanese government loan issues, referring to domestic Japanese financial conditions. Chapters Three to Seven examine the development of Japanese government loan issues on the international capital markets. -

Public Statement Relating to Settlement Agreement Between the Central Bank of Ireland and KBC Bank Ireland
Settlement Agreement between the Central Bank of Ireland and KBC Bank Ireland Plc KBC Bank Ireland Plc fined €1,400,000 by the Central Bank of Ireland for breaches of its Code of Practice on Lending to Related Parties The Central Bank of Ireland (the ‘Central Bank’) has fined KBC Bank Ireland Plc (‘KBC‘ or the ’Firm‘) €1,400,000 and reprimanded it for breaches of the Code of Practice on Lending to Related Parties 2010, and the Code of Practice on Lending to Related Parties 2013 (collectively ’the Code‘). The breaches have been admitted by the Firm. This is the first enforcement action brought by the Central Bank against a credit institution for breaches of the Code. The Central Bank introduced the Code in 2011 to guard against abuses in lending to related parties and as part of the Central Bank’s regulatory approach following the financial crisis. Under the Code, relevant firms must obtain the prior approval of their Board or a subcommittee thereof, before they can enter into, or vary loan transactions with related and/or connected parties, which include directors, senior managers, significant shareholders of the firm and spouses or domestic partners. The breaches of the Code occurred from 26 September 2012 to 23 February 2016, during which time the Firm failed, on eighteen separate occasions to: Have adequate policies and processes in place, which are adhered to, to identify loans to related parties; Obtain the prior approval of its Related Party Lending Committee prior to (i) granting a loan to a related party and (ii) extending the maturity dates on 12 separate occasions in respect of five existing loans; and Obtain prior approval of the Related Party Lending Committee on five separate occasions in respect of the management of four loans to two related parties. -
Cross-Border Financial Institutions in the EU: Analysis of Total Assets and Ultimate Ownership
Directorate-General for Internal Policies Directorate A - Economic and Scientific Policy Policy Department A.: Economic and Scientific Policy and Quality of Life Unit Cross-Border Financial Institutions in the EU: Analysis of Total Assets and Ultimate Ownership Briefing Note IP/A/ECON/NT/2008-10 PE 408.550 Only published in English. Author: Josina KAMERLING Policy Department Economy and Science DG Internal Policies European Parliament Rue Wiertz 60 - ATR 00L046 B-1047 Brussels Tel: +32 (0)2 283 27 86 Fax: +32(0)2 284 69 29 E-mail: [email protected] Arttu MAKIPAA Policy Department Economy and Science DG Internal Policies European Parliament Rue Wiertz 60 - ATR 00L042 B-1047 Brussels Tel: +32 (0)2 283 26 20 Fax: +32(0)2 284 69 29 E-mail: [email protected] Manuscript completed in August 2008. The opinions expressed in this document do not necessarily represent the official position of the European Parliament. Reproduction and translation for non-commercial purposes are authorised provided the source is acknowledged and the publisher is given prior notice and receives a copy. Rue Wiertz – B-1047 Bruxelles - 32/2.284.43.74 Fax: 32/2.284.68.05 Palais de l‘Europe – F-67000 Strasbourg - 33/3.88.17.25.56 Fax: 33/3.88.36.92.14 E-mail: [email protected] IP/A/ECON/NT/2008-10 PE 408.550 Table of Contents 1. The Data on Financial Institutions in EU27 ......................................................................1 2. Largest Financial Institutions in Europe (Tables 1-5) .......................................................2 -
2020 Sample Delegate List
2020 Sample Delegate List Join 600+ institutional and private investors alongside fund managers, developers, telecoms, energy companies and the world's governments for four days of unrivalled networking opportunities and cutting-edge content. Here is a sample of some of the biggest names in the industry who you could meet in March: • Arendt & Medernach • Ancala Partners • 3i Group • APFC • 4IP Group • APG Asset Management • A.P. Moller Capital • Apollo Global Management • Aarden • Aquila Capital Management • Abu Dhabi Investment Authority • Arcus Infrastructure Partners • ABVCAP • Ardian • Access Capital Partners • Arjun Infrastructure • Achmea Investment Management • Arpinge • Actis • ASFO • Africa Investor • Ashurst • Africa50 • Asian Infrastructure Investment Bank • Al Saheal Property Development & • Asper Investment Management Management • Astarte Capital Partners • Alberta Teachers' Retirement Fund • Asterion Industrial Partners • Alberta Teachers' Retirement Fund Board • Astrid Advisors • Allen & Overy • ATLAS Infrastructure • Allianz Capital Partners • ATP • Altamar Capital Partners • AXA Real Estate Investment Managers • AMF Pension • Axium Infrastructure • AMP Capital • Bain & Company • Analysys Mason • Barmenia For more information, visit the website here. Last updated 21/01/2020 • Basalt Infrastructure Partners • Cooperatie • Bases Conversion and Development • Copenhagen Infrastructure Partners Authority (BCDA) • Covalis Capital • BayWa r.e. renewable energy • CPPIB • bfinance • CPV-CAP Pensionskasse Coop • Bimcor • Credit -

Uncovering Opportunities in 2017 Deloitte Deleveraging Europe 2016 – 2017
Uncovering opportunities in 2017 Deloitte Deleveraging Europe 2016 – 2017 Financial Advisory Uncovering opportunities in 2017 | Deloitte Deleveraging Europe 2016 – 2017 Contents Introduction Introduction 01 The European loan portfolio market has regained much of the momentum it established over the last number of years. Uncertainty over the terms of Brexit and the US Presidential transition temporarily delayed deal Market overview 02 making in mid-2016, but the fundamental balance sheet and regulatory drivers of loan sale transactions proved stronger. Six months ago we forecast a second half resurgence in loan portfolio sales; that is what has Viewpoint: Risks and opportunities in 2017 06 happened, with more to come in 2017. United Kingdom and Ireland 07 By the numbers the leading European loan sale markets in reach something approaching a point of The record rate of loan disposals achieved in 2017. Portugal, which has yet to deliver a equilibrium. In the meantime we estimate Viewpoint: Banks still need to face reality 12 2015 has been repeated again in 2016, with significant deal flow, is likely to achieve more that there remains €2 trillion in unresolved Germany and the Netherlands just over €103 billion of completed deals for than the €1.8 billion of completed deals in non-core assets in Europe, suggesting that 13 the full year. Yet the Brexit-induced mid-year 2016, if pricing becomes more realistic. the loan sale market has the potential to Spain and Portugal 17 pause in dealmaking had an impact on the expand in 2017. final deal numbers. The number of ongoing Different markets, changing assets Italy 23 deals at the end of 2016 is considerable, with These markets will take the lead from Ireland Headline facts and figures 56 deals representing €70 billion by value. -

Cranfield 100 Women to Watch 2018
The Female FTSE Board Report 2018 - 100 Women to Watch 1 THE FEMALE FTSE BOARD REPORT 2018 100 WOMEN TO WATCH 2018 Dr Patricia Pryce, Director, Beauwest Consultancy Ltd; Visiting Fellow, Cranfield School of Management Jacey Graham, Director, Brook Graham (in association with Pinsent Masons); Visiting Fellow, Cranfield School of Management 2018 is a significant year for women in the UK. It marks 100 years since women (over the age of 30) gained the right to vote, the unveiling of the first statue of a female in Parliament Square (Millicent Fawcett) and the first time a royal princess (Princess Charlotte) gets to keep her position in line to the throne, despite the arrival of a baby brother (Prince Louis). And for the first time women’s representation on FTSE 100/250 boards hits a new high of 29%/23.7%. These figures provide evidence that talented women are increasingly ready to take up Executive and Board positions; however, such women are often not visible to decision-makers who influence shortlists for Non-Executive Director (NED) positions in FTSE 350 companies. In this, our ninth 100 Women to Watch supplement, we continue to showcase the broad and deep female talent pool for ‘UK plc’ to draw on. As always, we acknowledge that it is neither an exhaustive nor definitive list of the only talented women available for board positions; neither is it attempting to represent the best 100 women. Our profiles reflect a broad range of backgrounds and include women who hold senior executive roles in FTSE 350 firms and other significant organisations such as large non-listed companies, major charities, professional services firms, educational institutions and the Civil Service, and from many different disciplines and functions. -

FINANCIAL SERVICES.Pdf
INTERNATIONAL REFERENCES FINANCIAL SERVICES Algeria Bank of Algeria, Société Générale Algérie, BNP, Salama Bank of Blida Australia Bank of Scotland international Austria “Creditanstalt AG”, National Savings, “Oberbank”, “Raiffeisenkasse” banks France Barclay’s, Banque de France, Credit Lyonnais, Citibank, Credi Mutuel, CIAL of CIC group, Commerzbank Paris Germany Deutsche Bank, Berliner Bank, Commerzbank, Dresdner Bank Hungary National Bank (KFKI) Budapest Hong Kong Hong Kong bank Indonesia BNT Jakarta Italia Banks, Banca popolare di Bescia, Banca commerciale Italiana, Instituto bancario S. Paolo Torno, Banca popolare di Crema Ivory Coast Société Générale de Banque Morocco Banque Centrale Populaire, Commercial Bank of Morocco New Zealand Deutsche Bank Auckland Niger Banque Centrale des Etats d’Afrique de l’Ouest au Niger Norway Oslo Bank of Norway, Bank of Scotland international Philippines Zambales Subic Financial building corporation, Manilla Bangkok bank Portugal Banks Portugal, Pinto & Sotto Mayor, Portugues do Atlantico, Fonsecas & Burnay, Do Fomento, Acores, Uniao de bancos Portugueses, Caixa Geral de depositos, Stock exchange Lisbon Senegal Bank B.C.E.A.O. Dakar Serbia National Bank of Serbia Singapore City Bank South Africa South African Reserve Bank in Durban Spain Caja Rural de Granada, Cajamar, Banco BBVA, Banco Popular, Banca March, Bankinter, Caja Laboral, Unicaja, Caja de Ahorros de Ávila Thailand Bangkok Thai Farmers bank head office, Bangkok bank head office, Bangkok Bank of Ayudhya head office, Chiangmai Central bank of Thailand, Bank of Thailand, BTS Depot United Arab Emirates Abu Dhabi Barclays Bank, National bank of Abu Dhabi United Kingdom Barclays Bank London, Northern Trust London, Bank of England, Lloyds, Blue Crest, HSBC, Schroders. .